Learn how to avoid common money mistakes that can derail your financial future, from poor budgeting to ignoring long-term savings.
Managing personal finances can feel overwhelming at times, especially when unexpected expenses pop up or tempting offers seem too good to pass on. Many people fall into avoidable traps that drain their savings and create long-term stress. Understanding these pitfalls is the first step toward building a more secure financial foundation.
Skipping a Realistic Budget
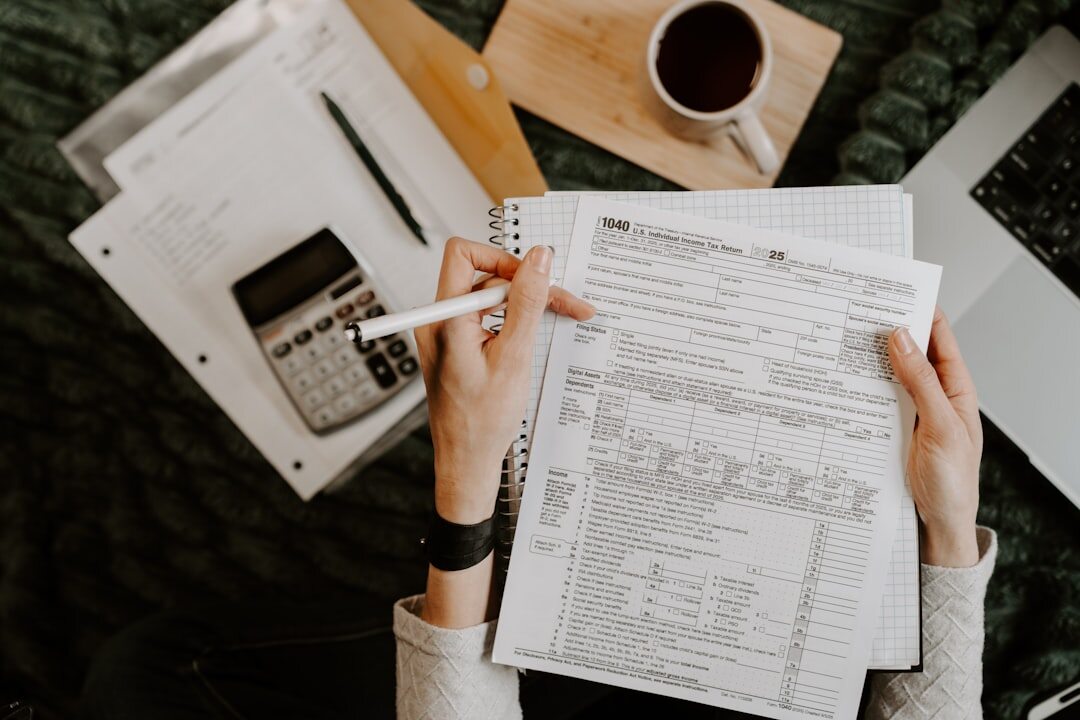
One of the biggest mistakes is operating without a clear budget. It is easy to assume you know where your money goes each month, but without tracking every expense, small purchases add up quickly. Start by listing all income sources and fixed costs like rent and utilities. Then categorize variable spending such as groceries and entertainment. Review your numbers weekly to catch overspending early. This simple habit prevents the shock of an empty account at month end.
Leaning on High-Interest Debt
Credit cards and payday loans often carry interest rates that compound faster than most investments grow. Paying only the minimum keeps you in a cycle of debt that lasts years. Instead, focus on paying off the highest-rate balances first while maintaining minimums on others. Consider balance transfers to lower-rate options if your credit allows it. The goal is to reduce principal aggressively rather than letting interest eat away at your progress.
Ignoring an Emergency Fund
Life rarely goes according to plan. A sudden car repair or medical bill can force reliance on credit if no cash reserves exist. Aim to set aside three to six months of essential expenses in a separate, easily accessible account. Begin with small automatic transfers until the fund reaches a comfortable level. This buffer protects your long-term goals from short-term disruptions.
Building wealth is less about earning more and more about keeping what you earn through smart choices.
Falling for Lifestyle Inflation
As income rises, many people upgrade their lifestyle instead of increasing savings. A bigger apartment or frequent dining out feels deserved, yet it leaves little room for future security. Commit to saving or investing a fixed percentage of every raise before adjusting spending. This maintains momentum toward retirement or other milestones without constant lifestyle creep.
Neglecting Retirement Contributions
Delaying retirement savings means missing out on compound growth over decades. Even modest monthly contributions grow substantially when started early. Take full advantage of employer matches and tax-advantaged accounts. Review your plan annually and increase contributions whenever possible. The earlier you begin, the less you need to save later to reach the same target.
Avoiding these pitfalls requires consistent attention rather than perfection. Track progress monthly, adjust as needed, and celebrate small wins along the way. Over time these habits create lasting financial stability and reduce stress around money decisions.